An examination of public records reveals professional connections among investors associated with short-selling campaigns against two bioplastics companies, alongside separate reporting about individuals linked to Novamont.
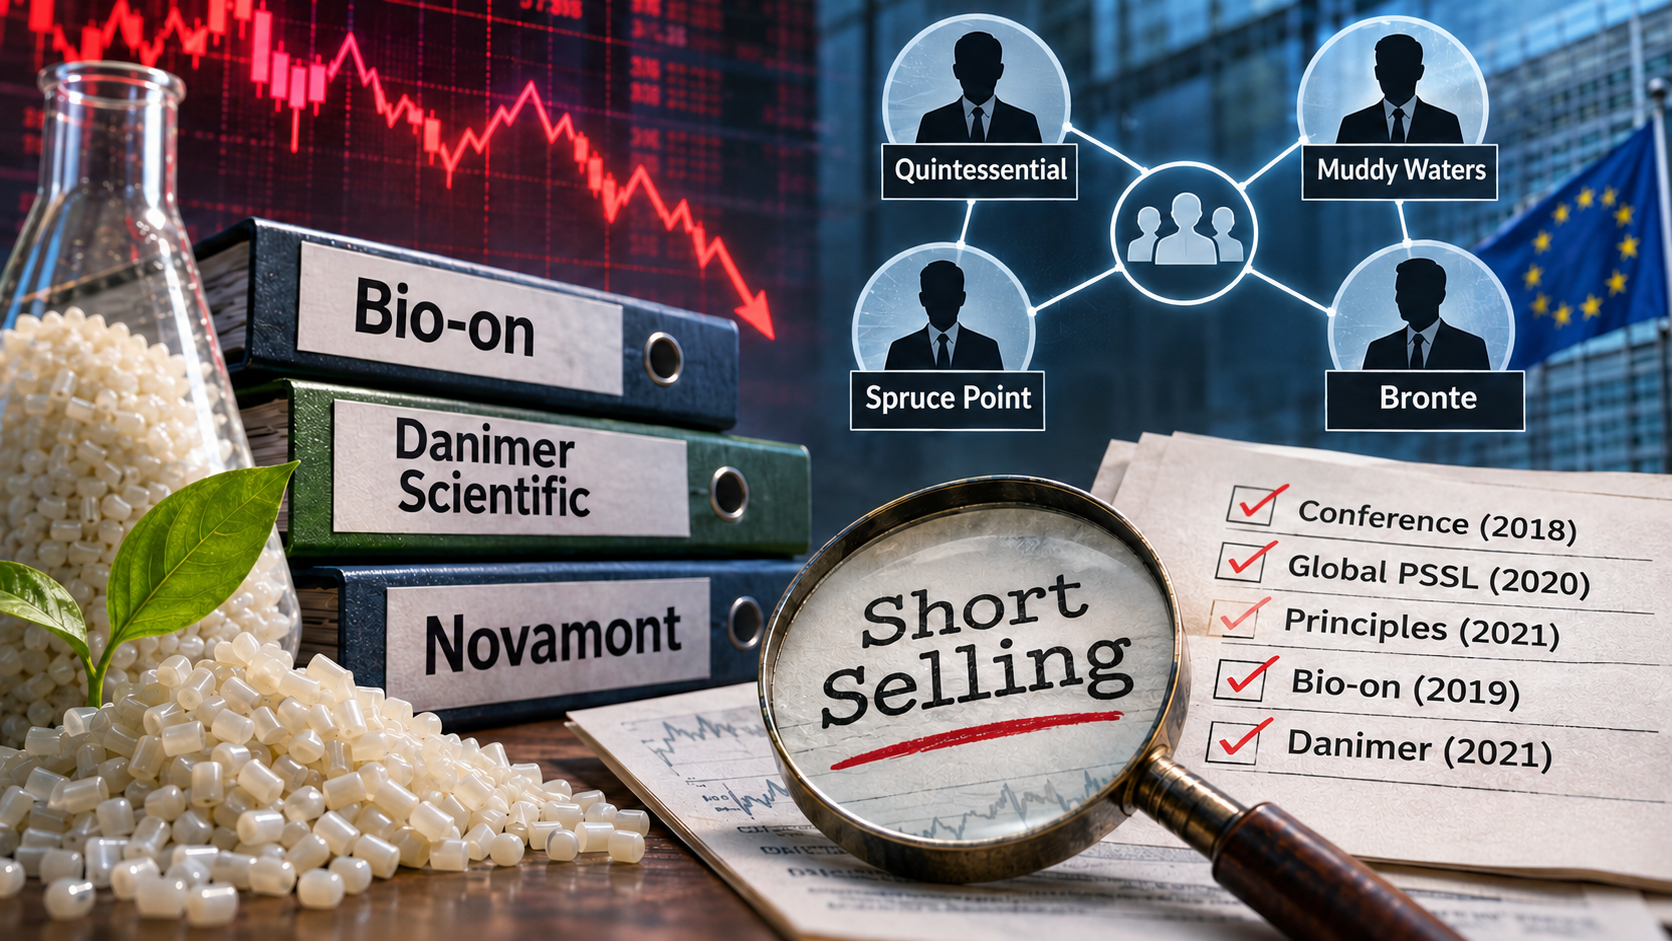
Summary. Two prominent PHA companies, Bio-on and Danimer Scientific, faced public short-selling campaigns followed by financial collapse. Records reveal overlapping industry relationships involving Quintessential, Muddy Waters, Spruce Point and Bronte Capital. A 2018 conference, a sustainable-finance working group, and Italian reporting on Novamont provide points of comparison. The documents demonstrate professional connections, not coordinated trading or a proven conspiracy.
Italy’s Bio-on, a developer of polyhydroxyalkanoate (PHA) technology, collapsed in 2019. US-based Danimer Scientific, also focused on PHA, filed for Chapter 11 bankruptcy protection in March 2025. Both faced public criticism from activist investors holding short positions, meaning they could profit if share prices declined.
The public record also establishes connections among several investment professionals: Gabriel (Gabriele) Grego of Quintessential Capital Management, Carson Block of Muddy Waters, Ben Axler of Spruce Point Capital Management and John Hempton of Bronte Capital. Those connections range from attendance at a short-selling conference to the formal co-chairing of a financial-industry working group.
Professional relationships are important to document. But they do not, on their own, establish coordinated trades, financial collusion, wrongdoing or responsibility for either company’s collapse.
1. May 2018: A common short-selling conference
On 3 May 2018, Kase Learning held The Art, Pain and Opportunity of Short Selling at the New York Athletic Club. Its published program listed Carson Block of Muddy Waters, Ben Axler of Spruce Point and Gabriel Grego of Quintessential among the speakers.
The event aimed to bring short sellers together to discuss their work and exchange ideas. It establishes that three investors later associated with the Bio-on and Danimer stories participated in the same professional gathering more than a year before Bio-on’s crisis. It does not establish that they discussed either company or agreed on future campaigns.
Source: Kase Learning conference program (2018).
2. July 2019: Quintessential challenges Bio-on
On 24 July 2019, Quintessential Capital Management publicly challenged Bio-on’s financial reporting, industrial activity and business prospects in research dated 19 July. Quintessential disclosed a financial interest in a fall in the company’s share price.
The report triggered an intense market confrontation. Bio-on rejected the allegations. Later in 2019, Italian authorities investigated the company’s reporting and management, and Bio-on entered insolvency proceedings. In November 2024, a first-instance criminal judgment convicted former executives; the defendants challenged the verdict, and appeal proceedings continued in 2026.
These events must be distinguished. A short-selling report, subsequent investigations, the company’s insolvency and the criminal proceedings are part of the chronology, but their proximity does not prove that the investor caused the collapse or that every criticism was correct.
Sources: Quintessential’s Bio-on report; ANSA on the October 2026 appeal proceedings.
3. Maurizio Salom, Quintessential and Novamont
One of the most consequential questions raised in Italy concerned Maurizio Salom, an accountant and corporate auditor involved in examining Bio-on’s accounts for the Quintessential research. Italian reporting identified Salom’s professional appointments in companies associated with Novamont, an established Italian bioplastics producer.
In July 2019, Wired Italia described Salom’s roles and reported the debate over potential conflicts of interest. Salom rejected the suggestion that his work for multiple companies created an improper conflict. In December 2024, Rai 3’s investigative program Report, in a segment entitled Il sogno di plastica, revisited those connections and examined further records.
Rai’s transcript also discussed Michele Casò, then associated with Novamont’s board of statutory auditors, who was later retained as a consultant to Bio-on’s bankruptcy trustee. Catia Bastioli, Novamont’s chief executive at the time, was another name examined by the program: according to Rai, her name appeared on a list of people whom Grego said he had consulted while preparing his Bio-on report.
That is not the same as establishing that Bastioli was employed or paid as Grego’s consultant. Nor do these professional links demonstrate that Novamont commissioned, financed or directed Quintessential’s short-selling research. The subject merits scrutiny precisely because roles, relationships and potential conflicts should be described accurately, not conflated with proof of misconduct.
Sources: Wired Italia, 27 July 2019; Rai Report, full transcript.
4. December 2020: A documented formal collaboration
In contrast to conference attendance, a later connection is explicit. On 15 December 2020, Securities Finance Times reported that Gabriel Grego, Carson Block and John Hempton would co-chair a working group for the Global Principles for Sustainable Securities Lending (Global PSSL), alongside its founder, Dr Radek Stech.
The group was called Short–Long Investments and ESG. Its stated purpose was to examine how short and long investment strategies intersect with environmental, social and governance considerations. These were specialist working-group roles, not evidence of jointly managing one fund or sharing trading positions.
This is the clearest documented institutional relationship between several figures in the present investigation. It shows they collaborated on an industry initiative. It does not prove that they collaborated on the Bio-on or Danimer trades.
Sources: Securities Finance Times, 15 December 2020; Global PSSL’s workstreams.
5. 2021: Short selling and sustainable-finance principles
Global PSSL subsequently promoted voluntary principles addressing securities lending, market practices, transparency and ESG. Quintessential and Muddy Waters appeared among its initial signatories in September 2021.
A related Global PSSL initiative promoted the idea that activist short selling could expose poor corporate governance or misleading claims. Such a philosophy is not intrinsically inconsistent with investigating companies whose products are marketed as sustainable. It does, however, make transparency about research, economic incentives and relationships especially important.
The industry principles establish a shared public framework, not a shared short-selling portfolio.
Sources: Global PSSL’s September 2021 signatories; Securities Finance Times on the ESG standard.
6. 2021–2025: Danimer Scientific and overlapping investors
Danimer Scientific became a target of multiple activist research reports in 2021. Spruce Point published critical material, including its 21 May report, questioning production figures, pricing and financial projections. Muddy Waters issued a separate report on 15 September 2021, criticizing Danimer’s representations about its commercial prospects and customer agreements.
Both investment firms disclosed short positions. Danimer contested their allegations. In a public response to Muddy Waters, the company described its claims as misleading and defended its operations.
Bronte Capital, associated with Global PSSL co-chair John Hempton, was subsequently reported to hold a disclosed short position in Danimer in early 2022. This adds another connection to the chronology, but ownership and trading data would be needed to determine whether positions overlapped in any meaningful way.
On 18 March 2025, Danimer filed for Chapter 11 protection. The bankruptcy followed years of financing, commercial and operational difficulties. The available evidence does not establish that the short sellers caused that outcome.
Sources: Spruce Point’s Danimer research; Muddy Waters’ Danimer report; Danimer’s response; US SEC bankruptcy disclosure.
7. Another shared target: e.l.f. Beauty
The overlap between Spruce Point and Muddy Waters is not restricted to Danimer. On 9 November 2023, Spruce Point published a short-selling report about cosmetics company e.l.f. Beauty, focusing in part on its vendor relationships. On 20 November 2024, Muddy Waters published a different report alleging issues with e.l.f.’s financial reporting. The company rejected Muddy Waters’ allegations.
The reports appeared about a year apart and concerned different subjects. Repeated interest in the same issuer is worth documenting, but it is not evidence that research or trades were coordinated.
Sources: Spruce Point’s e.l.f. research; Muddy Waters’ e.l.f. research.
8. A separate matter: Symphony Environmental
Symphony Environmental belongs in this discussion only as a separate example of regulatory and commercial conflict between plastics technologies. Symphony challenged the EU prohibition affecting oxo-degradable plastics, but the EU General Court dismissed its challenge in January 2024.
Our 4 November 2026 investigation into European Bioplastics and Novamont examined lobbying concerning competing plastics technologies. Those findings provide context; they do not establish that Novamont’s lobbying alone caused the restriction. We have found no verified organizational or financial connection between Symphony’s investors and the Bio-on or Danimer short sellers discussed here.
Sources: Court of Justice of the EU, January 2024; Bioplastics News investigation, 4 November 2026.
9. What has been established—and what has not
The documents establish a series of identifiable points: Grego, Block and Axler appeared at the same 2018 short-selling conference; Grego, Block and Hempton formally co-chaired a Global PSSL working group; Quintessential and Muddy Waters subscribed to common sustainable-finance principles; and Muddy Waters and Spruce Point separately targeted Danimer and, later, e.l.f. Beauty. Italian reporting also identified professional ties involving people connected to Quintessential’s Bio-on research and Novamont.
None of these facts establishes a single coordinated financial operation. We have not established common beneficial ownership of the funds, shared trading instructions, improper information exchanges, the profits each participant made or a causal chain linking the investors to either bankruptcy. Claims on those subjects would require transaction records and other evidence not presented here.
Conclusion: Document the relationships, test the claims
Activist short sellers can play a valuable role in revealing questionable accounts and business models. They also have an obvious financial incentive when they hold positions that gain value as shares fall. Those realities coexist.
Bio-on and Danimer show how consequential disputes over early-stage industrial technology can become. The public records add a specific, verifiable layer: some of the investment professionals involved were part of overlapping professional circles and even a formal industry working group.
That is a legitimate subject for investigative reporting. The documents establish relationships, not a conspiracy. Further conclusions about coordination, financial interests or misconduct must rest on evidence rather than inference.